

The Gulf’s meetings and events industry entered 2026 with extraordinary momentum. New venues, global conference brands launching regional editions, and aggressive national strategies promised another year of rapid growth. Yet in recent weeks the sector has encountered a familiar stress test: geopolitical instability and disrupted aviation.
For organizers across the GCC, the question is no longer whether the market will grow – but how resilient the ecosystem is when shocks occur.
The Gulf’s Events Boom Is Real - and Structural
Over the past three years, the Gulf has undergone a dramatic expansion in business events. The number of corporate and industry events across the region has effectively tripled, helping push the broader business travel market toward a projected $270 billion by 2030.
Dubai and Riyadh are leading the charge, supported by large infrastructure investments and international partnerships. Market forecasts suggest the UAE MICE sector could reach $9.26 billion by 2030, while Saudi Arabia’s market may grow to $5.33 billion.
Governments are not treating events as tourism side projects anymore. Across the GCC, exhibitions and conferences are increasingly embedded into national economic strategies – used to attract foreign investment, accelerate industry clusters, and position cities as global business hubs.
The scale of this ambition is visible in event calendars. Dubai World Trade Centre alone scheduled 71 international exhibitions and conferences in the first half of 2026, highlighting the city’s role as one of the world’s busiest business event destinations.
Meanwhile, Abu Dhabi’s ADNEC Group expects over 190 events in the same period, further reinforcing the Emirates’ dominance in regional MICE infrastructure.
In parallel, Saudi Arabia is trying to leapfrog competitors by positioning itself as the “most event‑friendly country in the world”, leveraging its experience managing massive pilgrimage logistics and investing heavily in venues and tourism ecosystems under Vision 2030.
A Sudden Stress Test
Despite the strong fundamentals, the past weeks have reminded organizers that the events industry remains highly sensitive to geopolitical shocks.
Recent regional tensions have disrupted flights, corporate travel, and event logistics across the Middle East. According to industry reporting, the resulting disruption is being described as the most significant business travel shock in the region since the Covid pandemic.
The effects are already visible:
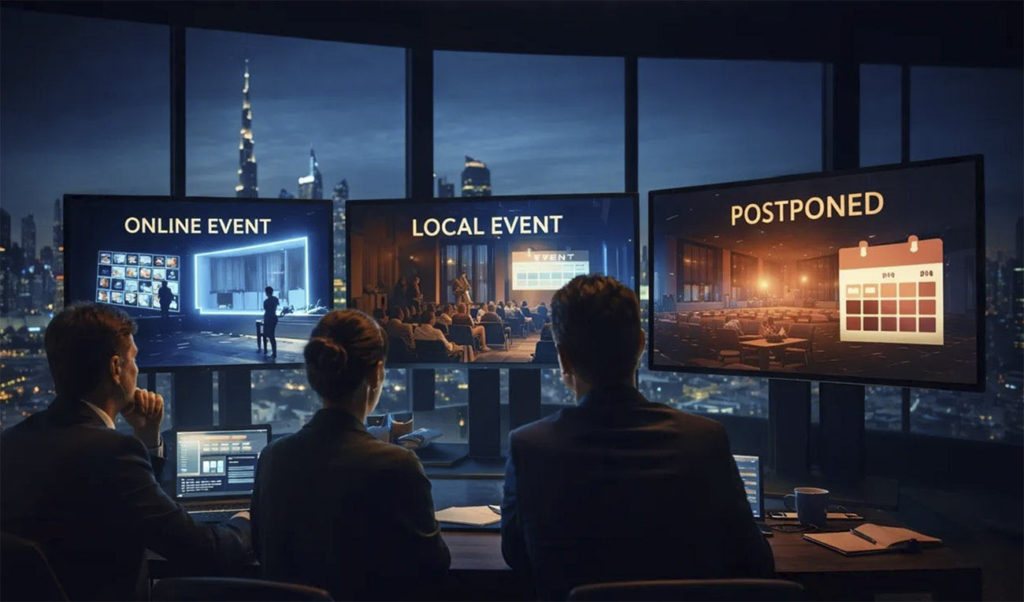
- international conferences being postponed
- airlines suspending or rerouting flights
- delegations reconsidering travel
- insurance and risk assessments tightening.
One high‑profile example is the Megacampus Summit in Dubai, which has already been postponed to later in the year due to regional instability. These developments are not unprecedented, but they highlight the fragility of global event logistics in a region that sits at the crossroads of Europe, Asia, and Africa.
The Real Risk: International Attendence
Interestingly, the biggest threat to GCC events is rarely venue availability or infrastructure.
It is international delegate confidence.
Recent destination sentiment models suggest that in the short term (March–June 2026), travel consideration from key markets could decline significantly:
UK: –18% to –24%
France: –25% to –32%
Spain: –28% to –34%
Domestic and regional markets, however, remain far more resilient. This reinforces a critical insight: the GCC events ecosystem is increasingly local and regional – not purely global.
What Smart Organizers Are Doing Now
The industry’s response is already evolving. Across the region, organizers are quietly adjusting their playbooks.
1. Building “dual‑scenario” events
Many conferences are planning two versions simultaneously:
– full international edition
– regional or hybrid fallback format.
This approach preserves sponsorship and content even if international travel weakens.
2. Leaning on regional audiences
Local participation from the GCC, India, and wider Asia is becoming a stabilizing force.
These markets often rebound faster and are less sensitive to geopolitical headlines.
3. Designing flexible event logistics
Contracts increasingly include:
– flexible dates
– hybrid participation options
– contingency venues.
The pandemic permanently changed how organizers structure risk.
4. Shortening booking windows
Many events are now confirming speakers and delegations closer to the event date, reducing exposure to geopolitical surprises.
The GCC’s Strategic Advantage
Despite short‑term disruptions, the long‑term outlook remains strong.
Few regions combine the Gulf’s unique advantages:
- world‑class aviation hubs
- massive investment in venues
- government support for the events economy
- geographic position between three continents.
Crucially, governments in the region see events as economic infrastructure, not just tourism products. That means the MICE sector will continue receiving funding, regulatory support, and international promotion – even during periods of instability.
The Outlook
The Gulf events industry is entering a new phase.
The growth story is intact. But the sector is also learning to operate in a world where geopolitics, aviation disruption, and market sentiment can shift quickly.
The winners will not simply be the biggest venues or the most ambitious mega‑events.
They will be the organizers who build resilient event models — flexible, regionalized, and capable of operating even when the sky briefly closes.
Related links:
https://micebook.com/blog/2026/03/04/global-travel-business-events-hit-by-middle-east-conflict/
https://www.c-mw.net/chaos-in-the-middle-east-forces-organisers-to-postpone-major-dubai-conference/
https://www.arabnews.com/node/2628209/business-economy
https://mediaoffice.ae/en/news/2026/january/05-01/71-events-at-dwtc-in-h1-2026